 Facebook
 X
 Pinterest
 Copy Link
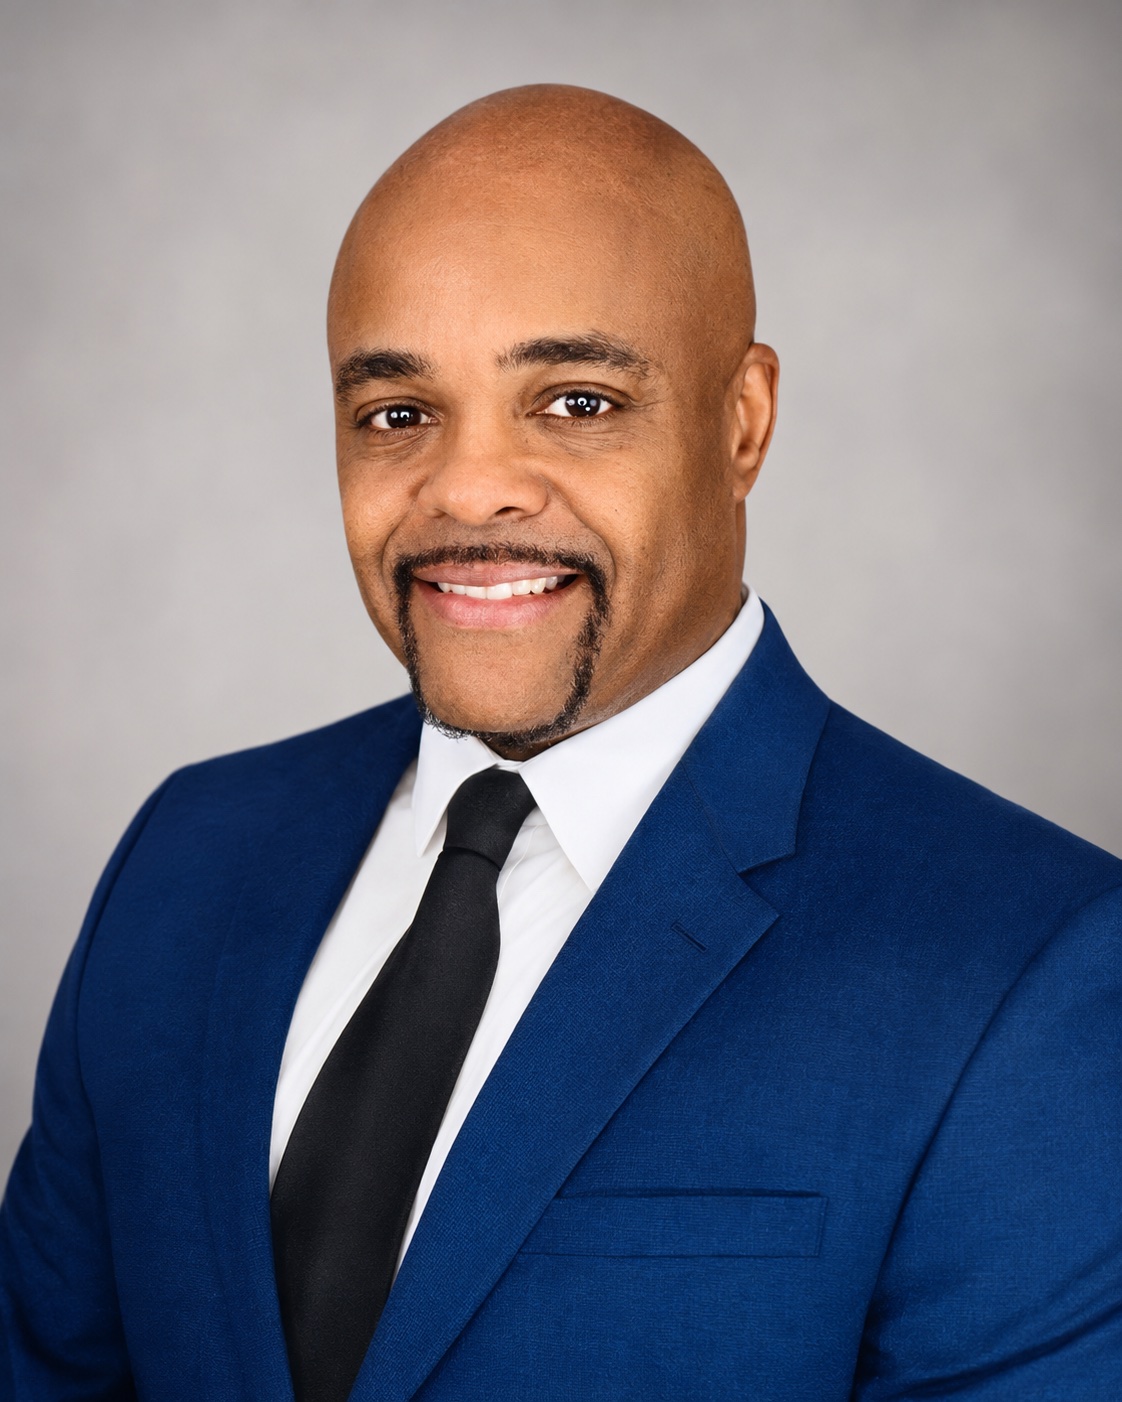
If you served, you earned one of the best home-buying tools out there — and a lot of veterans in Massachusetts never use it. I’m a Marine Corps veteran and a Realtor with CENTURY 21 North East, and I work with buyers across Bristol, Plymouth, and Norfolk counties. Here’s what you actually need to know about buying with a VA loan, without the sales pitch.
What a VA loan really gets you
- No down payment for most eligible buyers. That’s the headline benefit, and it’s real — you can buy with zero down and keep your savings for moving costs, repairs, and life.
- No private mortgage insurance (PMI). Conventional buyers with less than 20% down pay PMI every month. VA buyers don’t, which can save you hundreds a month.
- Competitive interest rates. VA loans typically price as well as or better than conventional loans for qualified buyers.
- Limits on closing costs. The VA restricts what lenders can charge you, and sellers can contribute toward your costs.
The funding fee — and the exemption many veterans miss
Most VA buyers pay a one-time VA funding fee, which can be rolled into the loan. But here’s the part that matters: veterans receiving VA disability compensation are exempt from the funding fee. If you’re a disabled veteran, that exemption can save you thousands at closing. Make sure your lender confirms your exemption status before you sign anything — it should be reflected on your Certificate of Eligibility.
Step by step: how the process works
- Get your Certificate of Eligibility (COE). This proves to the lender that you qualify. Your lender can usually pull it electronically in minutes, or you can request it through the VA.
- Get pre-approved by a lender who knows VA loans. Not every loan officer does many VA deals. Ask how many they’ve closed in the last year. A VA-savvy lender makes the process smoother for everyone — including the seller who’ll be reviewing your offer.
- House-hunt with the VA appraisal in mind. VA loans come with an appraisal and basic property condition standards. Older homes in our area sometimes need small repairs before closing — that’s manageable when your agent spots issues early instead of at the appraisal.
- Make your offer confidently. Some sellers still believe the myth that VA offers are weak. A good agent frames your offer properly: strong pre-approval, clear terms, and a lender who picks up the phone.
Why this matters in Southeastern Massachusetts
Home prices in our area mean a 20% conventional down payment can be $100,000 or more. Saving that while renting can take years — years where you’re not building equity. A VA loan lets an eligible veteran buy now, with no down payment and no PMI, in the same towns where they’d otherwise be priced out of starting.
Thinking about using your benefit?
Whether it’s your first home or your next one, I’ll walk you through it the same way I’d want it explained to me — straight answers, no pressure. I’m Clary Carson, CENTURY 21 North East, serving eastern Massachusetts.
Call or text: (508) 455-4728 · Email: clarycarson@hotmail.com


